




The latest CoreLogic data across Sydney’s Eastern Suburbs, Inner West and Lower North Shore highlights a Sydney property market where conditions continue to vary significantly by location, price point and property type. Prestige markets are generally experiencing longer selling campaigns and greater negotiation, while several Inner-City and Inner West suburbs continue to record relatively steady transaction activity.
Across the six suburbs analysed, 180 new sale listings were recorded during the past 60 days. Selling timeframes ranged from 41.24 days in Paddington to 82.3 days in Double Bay, while average vendor pricing outcomes varied from a 3.38% discount in Double Bay to a small 0.16% premium in Dulwich Hill.
As with our previous reports, new listings, recently advised sales and recently withdrawn advice are considered as separate CoreLogic measures. They have not been combined to calculate an absorption rate or sales-to-listings percentage, ensuring the analysis remains focused on the statistics as reported.
Market Summary – Last 60 Days
Across the six suburbs, the CoreLogic data recorded:
- New Listings: 180
- Total Advised Sales: 92
- Withdrawn Listings: 270
- Rental Listings: 732
Standout Metrics:
- Highest New Listing Activity: Dulwich Hill (62 listings)
- Shortest Average Selling Period: Paddington (41.24 days)
- Longest Average Selling Period: Double Bay (82.30 days)
- Largest Average Vendor Discount: Double Bay (-3.38%)
- Second-largest Average Vendor Discount: Annandale (-2.51%)
- Most Stable Positive Vendor Pricing Measure: Dulwich Hill (+0.16%)
- Largest Rental Market: Paddington (229 listings)
What This Means for Buyers
The latest figures reinforce why it pays to look beyond broad Sydney market headlines and work with an experienced Sydney buyers agent who understands each pocket of the city. Conditions differ considerably between the prestige eastern suburbs, tightly held harbour markets and more active inner-west locations.
In Double Bay, the combination of an 82.3-day average selling period and -3.38% average vendor discount suggests buyers may have greater opportunity to negotiate, particularly on properties with extended campaigns. Point Piper and Cremorne Point, meanwhile, remain extremely low-volume markets where individual property characteristics are more informative than broad suburb averages.
Paddington and Annandale are recording comparatively shorter selling periods, although both show some average vendor discounting. Buyers therefore need to balance the need to act on quality opportunities with disciplined assessment of price.
Dulwich Hill presents a different dynamic again, with the highest level of new listing activity in the dataset, a 46.51-day average selling period and pricing outcomes broadly around vendor expectations. This may provide buyers with greater choice while still requiring careful selection of individual assets.
Point Piper, NSW 2027
- New Sale Listings: 8
- Average Days on Market: 59.73 days
- Vendor Discount/Premium: 0.00%
- Recently Advised Sales: 3
- Withdrawn Listings: 15
- Total Rental Listings: 23
Key Insights:
Point Piper remains one of Australia’s most tightly held residential markets, where a very small number of transactions and the highly individual nature of prestige properties can result in considerable variation between reporting periods. Only eight new properties were listed during the reporting period, reinforcing the scarcity that characterises Point Piper. Properties spent just under 60 days on the market on average, reflecting the more considered nature of transactions at this end of Sydney’s property market.
The 0.00% average vendor discount indicates no recorded movement from vendor expectations on this measure, although the small sample size means the figure should be interpreted cautiously. The 15 recently withdrawn listings are also notable given the limited new listing activity, but should be considered independently rather than treated as part of the same listing cohort.
For buyers, Point Piper remains a property-by-property market. Position, harbour outlook, landholding, privacy and redevelopment potential can have a far greater influence on value than suburb-wide averages.
Double Bay, NSW 2028
- New Sale Listings: 21
- Average Days on Market: 82.30 days
- Vendor Discount: -3.38%
- Recently Advised Sales: 7
- Withdrawn Listings: 65
- Total Rental Listings: 132
Key Insights:
Double Bay continues to operate as a premium eastern suburbs market, although the latest figures suggest buyers are taking considerably longer to make purchasing decisions and are negotiating more firmly on price. The suburb recorded the longest average selling period in this report at more than 82 days. It also recorded the largest average vendor discount, at -3.38%. These two measures suggest buyers currently have more time to assess opportunities and may have greater negotiating scope where vendor expectations are not aligned with prevailing market conditions.
The 65 recently withdrawn listings also point to considerable stock leaving the market during the reporting period. This does not necessarily indicate weakness, as some vendors may simply be unwilling to meet current buyer expectations, particularly in a suburb where owners can often afford to wait.
For buyers, extended campaigns can be worth monitoring closely. Properties that have been available for several months may present opportunities for strategic negotiation, particularly where vendor circumstances or price expectations have changed.

Paddington, NSW 2021
- New Sale Listings: 45
- Average Days on Market: 41.24 days
- Average Vendor Discount: -1.44%
- Recently Advised Sales: 23
- Withdrawn Listings: 75
- Total Rental Listings: 229
Key Insights:
Paddington remains one of Sydney’s most consistently sought-after inner-city markets, underpinned by tightly held character housing, proximity to the CBD and strong lifestyle amenity. The suburb recorded the shortest average selling period in this dataset at just over 41 days. While this is not an exceptionally rapid selling environment, it compares favourably with the prestige markets analysed and suggests well-positioned properties continue to attract buyer attention within a reasonable timeframe.
The average vendor discount of -1.44% indicates some negotiation is occurring, but pricing movement remains relatively contained. With 75 recently withdrawn listings, there is also evidence of vendors choosing to leave the market rather than necessarily meet buyer expectations.
The suburb’s 229 rental listings represent the largest rental market in this report, reflecting Paddington’s broad appeal to tenants as well as owner-occupiers. For buyers, property quality remains particularly important, with renovated terraces, parking, aspect and location within the suburb capable of producing significantly different outcomes.
Cremorne Point, NSW 2090
- New Sale Listings: 7
- Average Days on Market: 48.13 days
- Average Vendor Discount: -0.46%
- Recently Advised Sales: 4
- Withdrawn Listings: 9
- Total Rental Listings: 43
Key Insights:
Cremorne Point remains a tightly held lower north shore market, prized for its harbour setting, proximity to the CBD and predominantly residential character. With only seven new listings during the period, available purchasing opportunities remain limited. Properties spent approximately seven weeks on the market on average, while the -0.46% vendor discount indicates very little movement from pricing expectations.
The relatively small number of listings and transactions means individual properties can have an outsized impact on suburb-level statistics. Nevertheless, the combination of limited new supply and minimal average discounting is consistent with the tightly held nature of Cremorne Point.
For buyers, patience is often required. Harbour views, building quality, parking, access and orientation can materially influence value, making detailed property-level analysis particularly important when opportunities do arise.
Annandale NSW 2038
- New Sale Listings: 37
- Average Days on Market: 43.63 days
- Vendor Premium: +2.51%
- Recently Advised Sales: 19
- Withdrawn Listings: 35
- Total Rental Listings: 127
Key Insights:
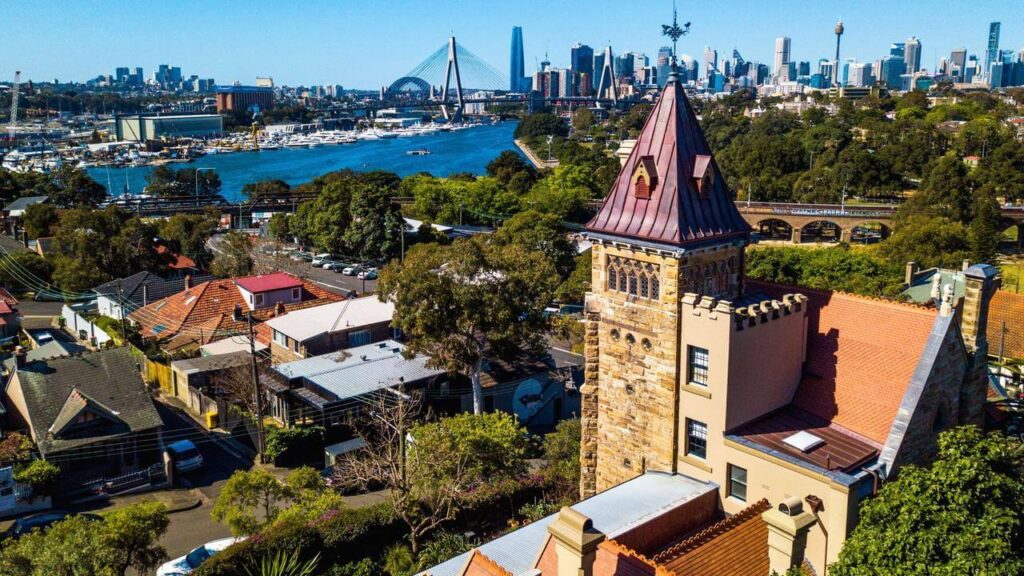
Annandale continues to appeal to buyers seeking character housing, established village amenity and proximity to the CBD, while retaining a distinctly residential atmosphere. Properties spent a little over six weeks on the market on average, placing Annandale among the faster-moving suburbs in this dataset. However, the average vendor discount of -2.51% was the second-largest recorded, indicating buyers are still negotiating meaningfully when establishing value.
This combination is particularly interesting for purchasers. Properties are not necessarily remaining available for extended periods, but the pricing data suggests buyers may still have scope to negotiate rather than feeling compelled to simply meet initial vendor expectations.
Annandale’s mix of terraces, freestanding homes and apartments also means performance can vary substantially by property type. For buyers, understanding the premium attached to parking, renovation quality, street position and land size remains essential.
Dulwich Hill, NSW 2203
- New Sale Listings: 62
- Average Days on Market: 46.51 days
- Average Vendor Premium: +0.16%
- Recently Advised Sales: 36
- Withdrawn Listings: 71
- Total Rental Listings: 178
Key Insights:
Dulwich Hill continues to provide an attractive proposition for buyers seeking inner-west lifestyle and connectivity at a comparatively accessible price point relative to some neighbouring suburbs. The suburb recorded the highest volume of new sale listings in this dataset, with 62 properties newly listed during the reporting period. Average selling time remained relatively contained at 46.51 days, while the +0.16% average vendor figure indicates pricing outcomes were broadly in line with expectations.
It was also the only suburb analysed to record a positive average vendor figure, albeit by a very small margin. Rather than suggesting widespread above-expectation sales, the figure is better interpreted as evidence of relatively stable pricing during the reporting period.
With 178 rental listings, Dulwich Hill also maintains a sizeable rental market. Its transport connectivity, village amenity and relative value within the inner west continue to make it attractive to owner-occupiers and investors alike.
Summary of August Insights
Overall, the data reinforces that the Sydney property market remains a collection of individual sub-markets rather than a single uniform market. Understanding days on market, pricing behaviour, available stock and the characteristics of the individual property remains critical to determining where genuine value exists.
At Rose and Jones Buyers Agents, we combine suburb-level market intelligence with detailed property analysis, local relationships and strategic negotiation to help clients make informed purchasing decisions across Sydney.
Ready to make your next move in Sydney’s property market? Get in touch with Byron Rose at Rose & Jones today for expert guidance tailored to your buying or investment goals.
Byron Rose
Director, Licensee-in-Charge & Buyers Agent, Rose & Jones
Data source: CoreLogic – Market Insights (Last 60 Days).